A hurricane deductible in Florida works differently from the regular deductible on a homeowners policy. Instead of a fixed amount, it’s usually a percentage of the dwelling coverage limit. Florida law allows options of 2, 5 and 10 percent, with some exceptions. On a home with a high dwelling limit, a percentage deductible can be much larger than homeowners expect.
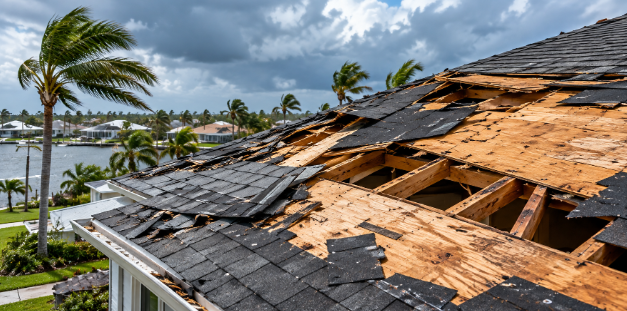
The hurricane deductible applies to losses caused by a hurricane, as defined in the policy and Florida Statutes section 627.4025. That generally covers damage from the time a hurricane watch or warning is issued for any part of Florida until 72 hours after the watch or warning ends. Damage from a tropical storm that never reaches hurricane strength usually falls under the regular all-other-perils deductible.
Florida also applies the hurricane deductible on a season basis. Once a homeowner has met it during a calendar year, a second hurricane that year typically triggers the smaller of the remaining hurricane deductible or the regular deductible. Keeping records of the first claim helps prove what was already met.
Flood damage is separate. A homeowners policy, including its hurricane deductible, generally doesn’t cover storm surge or rising water. That falls under a flood policy with its own deductible.
Jenkins Law P.L., a St. Petersburg firm that handles hurricane claims, recommends checking the declarations page before storm season to see which percentage applies. After a storm, homeowners should still report damage promptly, even if they think it falls below the deductible, because hidden damage often shows up later.
*This article is general information and not legal advice. Every claim is different. The hiring of a lawyer is an important decision that should not be based solely on advertisements.*